Ai Overview
Recurring software bills and fast-moving media budgets create a real control problem for finance teams. The issue gets harder in crypto-native businesses, where treasury may sit in stablecoins while vendors still expect card payments. It is making the right payment, on time, with the right budget rules, while still keeping clear oversight. For exchanges, wallets, fintech apps, and agencies, the challenge is not just making a payment.
Key Takeaways
- Stablecoin virtual cards help crypto-native teams pay for SaaS subscriptions and ad spend without relying on shared corporate cards or slow reimbursement flows.
- Instant virtual card issuance makes it easier to launch campaigns, renew software, and allocate budgets without delaying teams.
- Separate cards for vendors, campaigns, or departments improve budget control, reduce payment risk, and simplify reconciliation.
- Nadcab Crypto Cards supports USDT and USDC funding across five networks, plus controls like freezes, spend limits, transaction history, API access, and webhooks.
- Exchanges, wallets, fintech apps, and agencies can use a white-label card program to offer branded spending infrastructure under their own domain.
Recurring software bills and fast-moving media budgets create a real control problem for finance teams. The issue gets harder in crypto-native businesses, where treasury may sit in stablecoins while vendors still expect card payments. Stablecoin virtual cards help bridge that gap by giving teams a faster way to pay for SaaS tools, ad accounts, testing platforms, domains, cloud services, and one-off digital purchases without waiting for manual reimbursement or bank transfer workarounds.
For exchanges, wallets, fintech apps, and agencies, the challenge is not just making a payment. It is making the right payment, on time, with the right budget rules, while still keeping clear oversight. A single corporate card shared across departments creates risk. Reimbursement flows slow teams down. Manual top-ups create confusion when campaigns need to launch today, not next week.
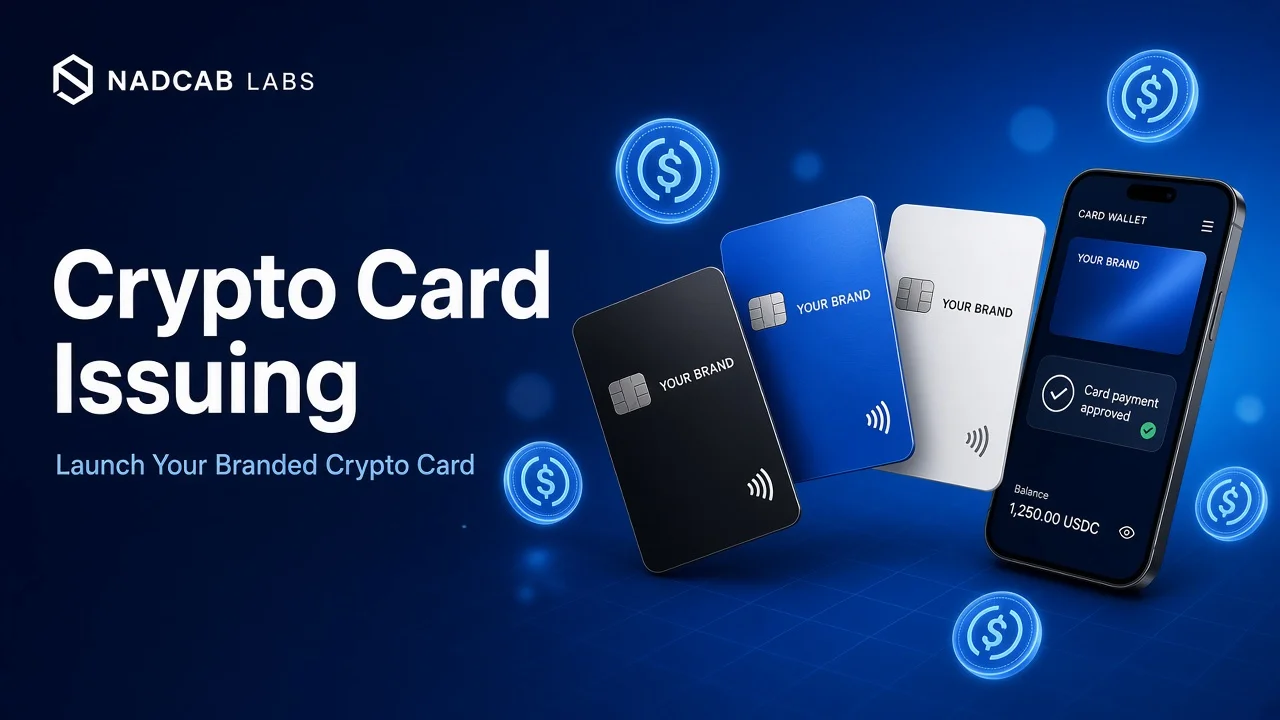
This is where a stablecoin-funded card setup becomes practical. With Nadcab Crypto Cards, businesses can issue branded virtual and physical Visa and Mastercard cards, fund spending with USDT or USDC across Ethereum, Polygon, BNB Smart Chain, Tron, or Solana, and manage controls through a console or API. That gives product, growth, and finance teams a card workflow that fits how crypto-native operations already move money.
Why SaaS and ad spend break traditional payment workflows
SaaS subscriptions and advertising spend do not behave like standard monthly supplier invoices. They are fragmented, time-sensitive, and often owned by different teams. Marketing may need several cards for campaign testing. Product teams may need separate cards for analytics, hosting, and developer tools. Operations may need cards for communication platforms, support tools, and automation software.
Traditional payment workflows often break because they were designed for slower approval cycles. A purchase request goes to finance, finance checks budget, someone shares a card or processes a manual payment, then accounting tries to match the charge later. That may work for planned procurement, but it is a poor fit for ad accounts that need immediate funding or software tools that start billing the moment a trial converts.
Crypto-native businesses face an extra layer of friction. Treasury may already be held in stablecoins, while vendors bill in fiat through card rails. Converting funds manually every time a team needs a card payment adds operational drag. It also creates avoidable delays for growth experiments and recurring software renewals.
Common friction points
- One shared card used across multiple teams and vendors
- Little control over who can use the card and for what
- Difficulty isolating failed charges or fraud exposure
- Slow approval loops for urgent ad or software purchases
- Manual reconciliation between treasury, card use, and subscriptions
- No clean way to separate campaign budgets or vendor-level limits
These issues are exactly why many teams move from a single company card model to a virtual card model. The value is not just convenience. It is structure.
What stablecoin virtual cards solve for crypto-native teams
Stablecoin virtual cards connect crypto treasury with everyday card acceptance. A business deposits USDT or USDC, then issues cards for defined use cases. Instead of routing spending through personal cards, reimbursements, or a single finance-controlled card, each team or workflow can have its own payment instrument.
For example, an agency could assign one card per client ad account. A wallet app could assign separate cards for app store spend, cloud credits, and compliance tooling. An exchange could issue cards to internal departments with different limits and policies.
This creates a cleaner operating model:
| Payment workflow | What usually happens | What a stablecoin virtual card setup changes |
|---|---|---|
| Recurring SaaS billing | Multiple tools charge the same shared card | Each subscription or vendor can have its own dedicated card |
| Ad campaign launch | Team waits for finance access or reimbursement | Finance issues a card instantly with a defined budget |
| Vendor offboarding | Finance must replace the main card everywhere | Only the affected card is frozen or replaced |
| Budget control | Review happens after spend occurs | Limits can be set before spend starts |
| Crypto treasury use | Manual conversion or ad hoc card funding | USDT or USDC funding aligns better with crypto-native operations |
Funding a wallet with USDT or USDC on Nadcab Crypto Cards is designed for this exact bridge. Businesses can deposit from five supported networks, then issue cards for online purchases and, on eligible plans, physical card use. For teams already operating in stablecoins, that can simplify how spend reaches vendors that only accept card payments.
If you want a broader view of program design, Nadcab Labs also covers the operating model in Stablecoin-Funded Virtual Card Program for Teams.
How instant card issuance improves campaign and software purchasing
Speed matters when spend is tied to growth, delivery, or uptime. If a campaign manager finds a winning audience segment, they should not have to wait for a card handoff. If a critical SaaS plan needs renewal to avoid service interruption, finance should not need to reroute procurement through manual steps.
Instant issuance changes this. Virtual cards can be created and used for online payments as soon as they are issued. That supports a much cleaner purchase flow for urgent or distributed teams.
Where instant issuance helps most
- Ad buying: launch a new campaign card for a market, platform, or client
- Software trials: test a vendor using a ring-fenced budget instead of exposing a main card
- Team onboarding: give a department its own spending method on day one
- Project-based work: issue temporary cards for a launch, sprint, or event
- Subscription containment: isolate recurring billing to one vendor-specific card
With Nadcab’s card issuing flow and API, teams can also issue in bulk, up to 100 cards at a time. That is useful when an agency wants separate cards for many client campaigns or when a finance team wants to pre-allocate cards by function, geography, or business unit.
For businesses building card features into their own product, the white-label option can go further by letting users access the card program through a branded cardholder web app on the company’s own domain. More on that below.
Using card controls for budgets, freezes and team-level limits
The real power of virtual cards is not just issuance. It is control. Good card programs let finance move from reactive monitoring to proactive rules.
Stablecoin-funded virtual cards are especially useful here because crypto-native teams often need to move quickly without losing oversight. A marketing lead may need spending autonomy, but finance still needs enforceable boundaries. A product manager may need to run several tools, but the company should still be able to freeze the card immediately if a vendor is no longer approved.
Core controls that matter in practice
- Freeze and unfreeze: pause a card when a campaign ends, a team member leaves, or suspicious activity needs review
- Spend limits: set a budget ceiling per card instead of relying on post-spend reconciliation
- Transaction history: review each card’s activity separately for cleaner bookkeeping and internal review
- Console and API management: allow finance and product systems to apply the same rules consistently
Nadcab Crypto Cards supports freeze controls, spend limits, and full transaction history from the console or the API. That matters because different organizations manage spend differently. Some finance teams want direct dashboard control. Others want to push policies from internal systems using automation.
A simple budget control checklist
| Use case | Recommended setup | Why it helps |
|---|---|---|
| Single SaaS subscription | One reusable card with a clear limit | Prevents unrelated vendors charging the same card |
| Short campaign test | Temporary card with a capped budget | Contains risk if spend needs to stop fast |
| Department software stack | Separate cards by vendor category | Makes reconciliation and ownership clearer |
| Employee role change | Freeze old card and issue a new one | Avoids sharing credentials or editing many vendors later |
| Client media buying | Card per client or campaign group | Improves budget separation and reporting |
This model also reduces the operational blast radius of a problem. If one card fails, reaches its limit, or needs to be paused, the rest of the program can continue normally.
Single-purpose vs reusable cards for subscriptions and media buying
Not every card should be used the same way. The right setup depends on the spending pattern.
Single-purpose cards
A single-purpose card is dedicated to one vendor, one subscription, one campaign, or one specific workflow. This is often the cleanest choice when you want tight controls and easy accountability.
Examples:
- A card used only for a cloud hosting bill
- A card dedicated to one ad account for a product launch
- A card used only for domain renewals
- A card assigned to one testing tool during a trial period
Best for: minimizing risk, improving reconciliation, and isolating vendor failures.
Reusable cards
A reusable card can support a team, function, or category over time. It is useful when the same team needs flexibility across several related purchases and there is a clear owner.
Examples:
- A growth team card for recurring creative tools
- An operations card for support and communication software
- A product team card for developer tool subscriptions
Best for: ongoing operational spend where strict ownership exists but one-vendor-per-card would be too rigid.
How to choose
- List the vendors or spend flows that cause the most confusion today.
- Identify whether each one is recurring, experimental, or high risk.
- Assign single-purpose cards to high-risk or hard-to-reconcile spend.
- Use reusable cards for stable categories with one accountable team owner.
- Apply limits and freeze rules before the cards are distributed.
- Review transaction history regularly and split any card that becomes too broad.
For many organizations, the strongest model is a mix of both. Single-purpose cards keep recurring SaaS billing contained, while reusable cards support faster day-to-day team purchases.
White-Label program
Your brand on the card. Your app on your domain.
Upload your logo, pick your colors and name your card, then launch a cardholder app on your own domain with two DNS records. Nadcab runs issuing and compliance while you own the customer relationship.
Custom card designYour domainMonthly or yearly plansPay from your wallet
How branded card programs fit exchanges, wallets and agencies
For some businesses, virtual cards are not only an internal finance tool. They are also a product feature or client service. That is especially relevant for exchanges, Web3 wallets, fintech apps, and agencies serving multiple end users or customers.
A branded card program can help these businesses offer controlled spending infrastructure under their own identity. Instead of sending users to a separate payment experience, the company can present cards with its own logo, colors, and card name.
With the Nadcab White-Label card program, businesses can launch a cardholder web app on their own domain using two DNS records, while Nadcab runs issuing and compliance. Programs use verified cardholders and require approved KYB for the business, which is an important point for compliant program design.
Where branded programs make sense
- Exchanges: give business users a spending layer connected to stablecoin treasury flows
- Wallets: extend from storage and transfer into controlled everyday card spend
- Agencies: offer clients dedicated ad spend cards with cleaner separation and reporting
- Fintech apps: package card access as part of treasury or expense workflows
If your team is considering the infrastructure side of this model, the Nadcab Labs guide on how to launch your own branded crypto debit card program is a useful starting point.
What developers need from a card API and webhook workflow
When cards become part of an operating system rather than a manual finance tool, developer features matter. Product and engineering teams need a clean way to create cards, apply controls, receive status updates, and connect transaction events to internal ledgers or approval logic.
The basics are straightforward: an API endpoint to create cards, authentication controls, and webhooks for state changes. In practice, teams should also think about permissioning, monitoring, and how card events map to treasury records.
Developer checklist
- REST API for card creation and management
- Webhook support for transaction and lifecycle events
- API keys and IP whitelisting for secure access
- Clear ownership model between finance operators and system automation
- Consistent internal IDs for cards, teams, vendors, and cost centers
Nadcab provides a REST API, webhooks, API keys, and IP whitelists. Even a simple endpoint structure like POST /v1/cards can unlock useful automation when connected to your own workflows.
Example workflow
1. User or team requests a new campaign budget
2. Internal system approves the request
3. App calls POST /v1/cards to issue a virtual card
4. Card ID is mapped to campaign ID and budget owner
5. Spend limit is applied
6. Webhook events update transaction records and alerts
7. Finance reviews activity in the console and internal reporting
This is especially relevant for platforms building embedded treasury, wallet, or spend features. If your product team is evaluating architecture choices around wallet and backend connectivity, these Nadcab Labs reads may help: Crypto Wallet API vs RPC, TRON RPC compatibility guide, and crypto wallet development services.
Transparent pricing
See exactly what your card program will cost
- 0% fee on card transactions
- Card issuing from $1 on the Custom plan
- Virtual cards instantly; physical cards with ATM withdrawals on KYC Growth plans and above
- Visa and Mastercard BINs with 3-D Secure on supported BINs
How to launch a stablecoin-funded card program with less overhead
Launching a card program does not need to start with a full custom infrastructure build. For many teams, the faster route is to use a platform that already handles issuing operations and compliance while letting the business control branding, user experience, and card logic.
Nadcab Crypto Cards is practical here because it covers the core pieces teams usually need first: branded Visa and Mastercard card issuing, stablecoin funding with USDT or USDC on five networks, instant virtual card issuance, support for Apple Pay and Google Pay on ready BINs, 3-D Secure on supported BINs, and optional physical cards with ATM cash withdrawals on KYC Growth plans and above.
The path can be simple:
- Create an account and explore the free trial.
- Complete business verification for KYB approval.
- Fund your wallet with USDT or USDC using a supported network.
- Choose whether you need internal team cards or a white-label end-user program.
- Issue virtual cards individually or in bulk.
- Apply spend limits, freeze rules, and ownership policies.
- Connect your application through API and webhooks if you need automation.
- Expand to physical cards if your approved plan and use case require them.
Pricing and plan structure matter when you move from testing to scale, so it helps to review the card plans and pricing early. Nadcab states card issuing from $1 on the Custom plan, 0% fee on card transactions, and a 3 days free trial, which can make it easier to validate the workflow before rolling it out across teams.
For businesses comparing internal finance operations with broader payable automation, Nadcab Labs also has a related guide on stablecoin-funded virtual cards for AP automation. And if your roadmap includes a wider financial product stack, Nadcab’s crypto banking development offering may be relevant.
Keep reading
Final Thoughts
SaaS subscriptions and ad spend move too quickly for shared-card workflows and manual reimbursement processes. Crypto-native teams need payment methods that match the speed of online spending while keeping budget control intact. That is why stablecoin virtual cards are becoming such a practical operating tool for finance, growth, and product teams.
The strongest setups combine instant issuance, vendor or team-level card separation, clear spending limits, and simple freeze controls. For exchanges, wallets, fintech apps, and agencies, the model can also extend into a branded card program that fits their own product and customer experience.
Nadcab Crypto Cards gives teams a direct way to put that model into practice: fund with USDT or USDC, issue branded virtual cards quickly, manage controls through the console or API, and scale into a white-label program when needed. Regulations and program requirements vary by jurisdiction, so businesses should plan their rollout accordingly, but the operational case is already clear: stablecoin-funded card infrastructure can make software and media spend faster to run and easier to control.
Frequently Asked Questions
Q1.What are stablecoin virtual cards?
Stablecoin virtual cards are payment cards funded from stablecoin balances such as USDT or USDC, then used for online card payments where cards are accepted. They help crypto-native businesses connect on-chain treasury with everyday vendor spending, especially for SaaS subscriptions, cloud tools, domains, and advertising accounts.
Q2.Why are stablecoin virtual cards useful for ad spend and SaaS billing?
They let finance teams issue dedicated cards quickly, apply limits before spend happens, and isolate payments by vendor, campaign, or department. That means fewer shared-card problems, faster approvals for urgent purchases, and better visibility into recurring billing without forcing teams into manual reimbursement or slower payment methods.
Q3.Should I use one card for all subscriptions or separate cards per vendor?
In most cases, separate cards per vendor or per spend purpose are easier to manage. A dedicated card reduces the impact of failed renewals, fraud concerns, and offboarding changes. Reusable cards still make sense for broader team-level spending, but only when ownership and budget limits are clearly defined.
Q4.What developer features matter in a card issuing platform?
Teams usually need a REST API for card creation and control, webhook support for transaction events, secure authentication such as API keys and IP whitelists, and enough structure to map cards to teams, vendors, or campaigns. Those features help connect card activity with approval workflows, treasury records, and internal reporting.
Q5.How do I start with Nadcab Crypto Cards?
Start by creating an account on Nadcab Crypto Cards and using the free trial to review the workflow. After approved KYB, you can fund your wallet with USDT or USDC on a supported network, issue virtual cards for your team, set limits and freezes, and then add API or white-label components if your use case needs deeper integration.
Explore Services
Related Services
Reviewed by
Aman Vaths
Founder of Nadcab Labs
Aman Vaths is the Founder & CTO of Nadcab Labs, a global digital engineering company delivering enterprise-grade solutions across AI, Web3, Blockchain, Big Data, Cloud, Cybersecurity, and Modern Application Development. With deep technical leadership and product innovation experience, Aman has positioned Nadcab Labs as one of the most advanced engineering companies driving the next era of intelligent, secure, and scalable software systems. Under his leadership, Nadcab Labs has built 2,000+ global projects across sectors including fintech, banking, healthcare, real estate, logistics, gaming, manufacturing, and next-generation DePIN networks. Aman’s strength lies in architecting high-performance systems, end-to-end platform engineering, and designing enterprise solutions that operate at global scale.